Asia Europe Market Enters Post-Holiday Rate Recovery Phase
October 19, 2026
The Asia-Europe trade has entered a post-National Day holiday phase marked by modest rate increases that landed below carrier expectations and differentiated cargo loading across alliances. Week 43 rates rose moderately from Week 42 lows, with GEMINI alliance pricing showing moderate increases and Ocean Alliance positioning at higher levels, though actual settlement prices remained substantially lower after discounts. Maersk’s Week 43 Shanghai-Europe base rate represented a moderate increase but fell short of the announced GRI target, with offline settlements reflecting weak downstream acceptance. The market’s central tension lies between carriers’ late October GRI announcements and uncertain post-holiday cargo momentum, with success dependent on end-October shipping intensity as cargo rushes to arrive before Christmas holidays.
To help you better understand the current market dynamics and support your sales activities at origin, please find below our latest market observations and outlook for the second half of October.
Rate Direction and Carrier Pricing Strategy
Week 43 rates showed modest increases across alliances, though the magnitude fell short of carrier GRI announcements. Market acceptance remained constrained by weak downstream demand, reflecting limited downstream acceptance as demand-side support weakened from Week 43 onward.
GEMINI alliance Week 43 pricing showed modest increases, though actual market acceptance remained substantially below published rates due to settlement-stage discounting. Hapag-Lloyd online quotations maintained premium positioning within the alliance.
Ocean Alliance carriers announced late October rate increases, with pricing differentiated by volume tier and booking channel, demonstrating the alliance’s coordinated upward pricing direction.
Premier Alliance maintained the most competitive positioning, though official post-10/19 rates remain unpublished. Yang Ming maintained competitive positioning with selective voyage-level pricing, actively pursuing cargo at lower levels. ONE North China held pre-holiday pricing.
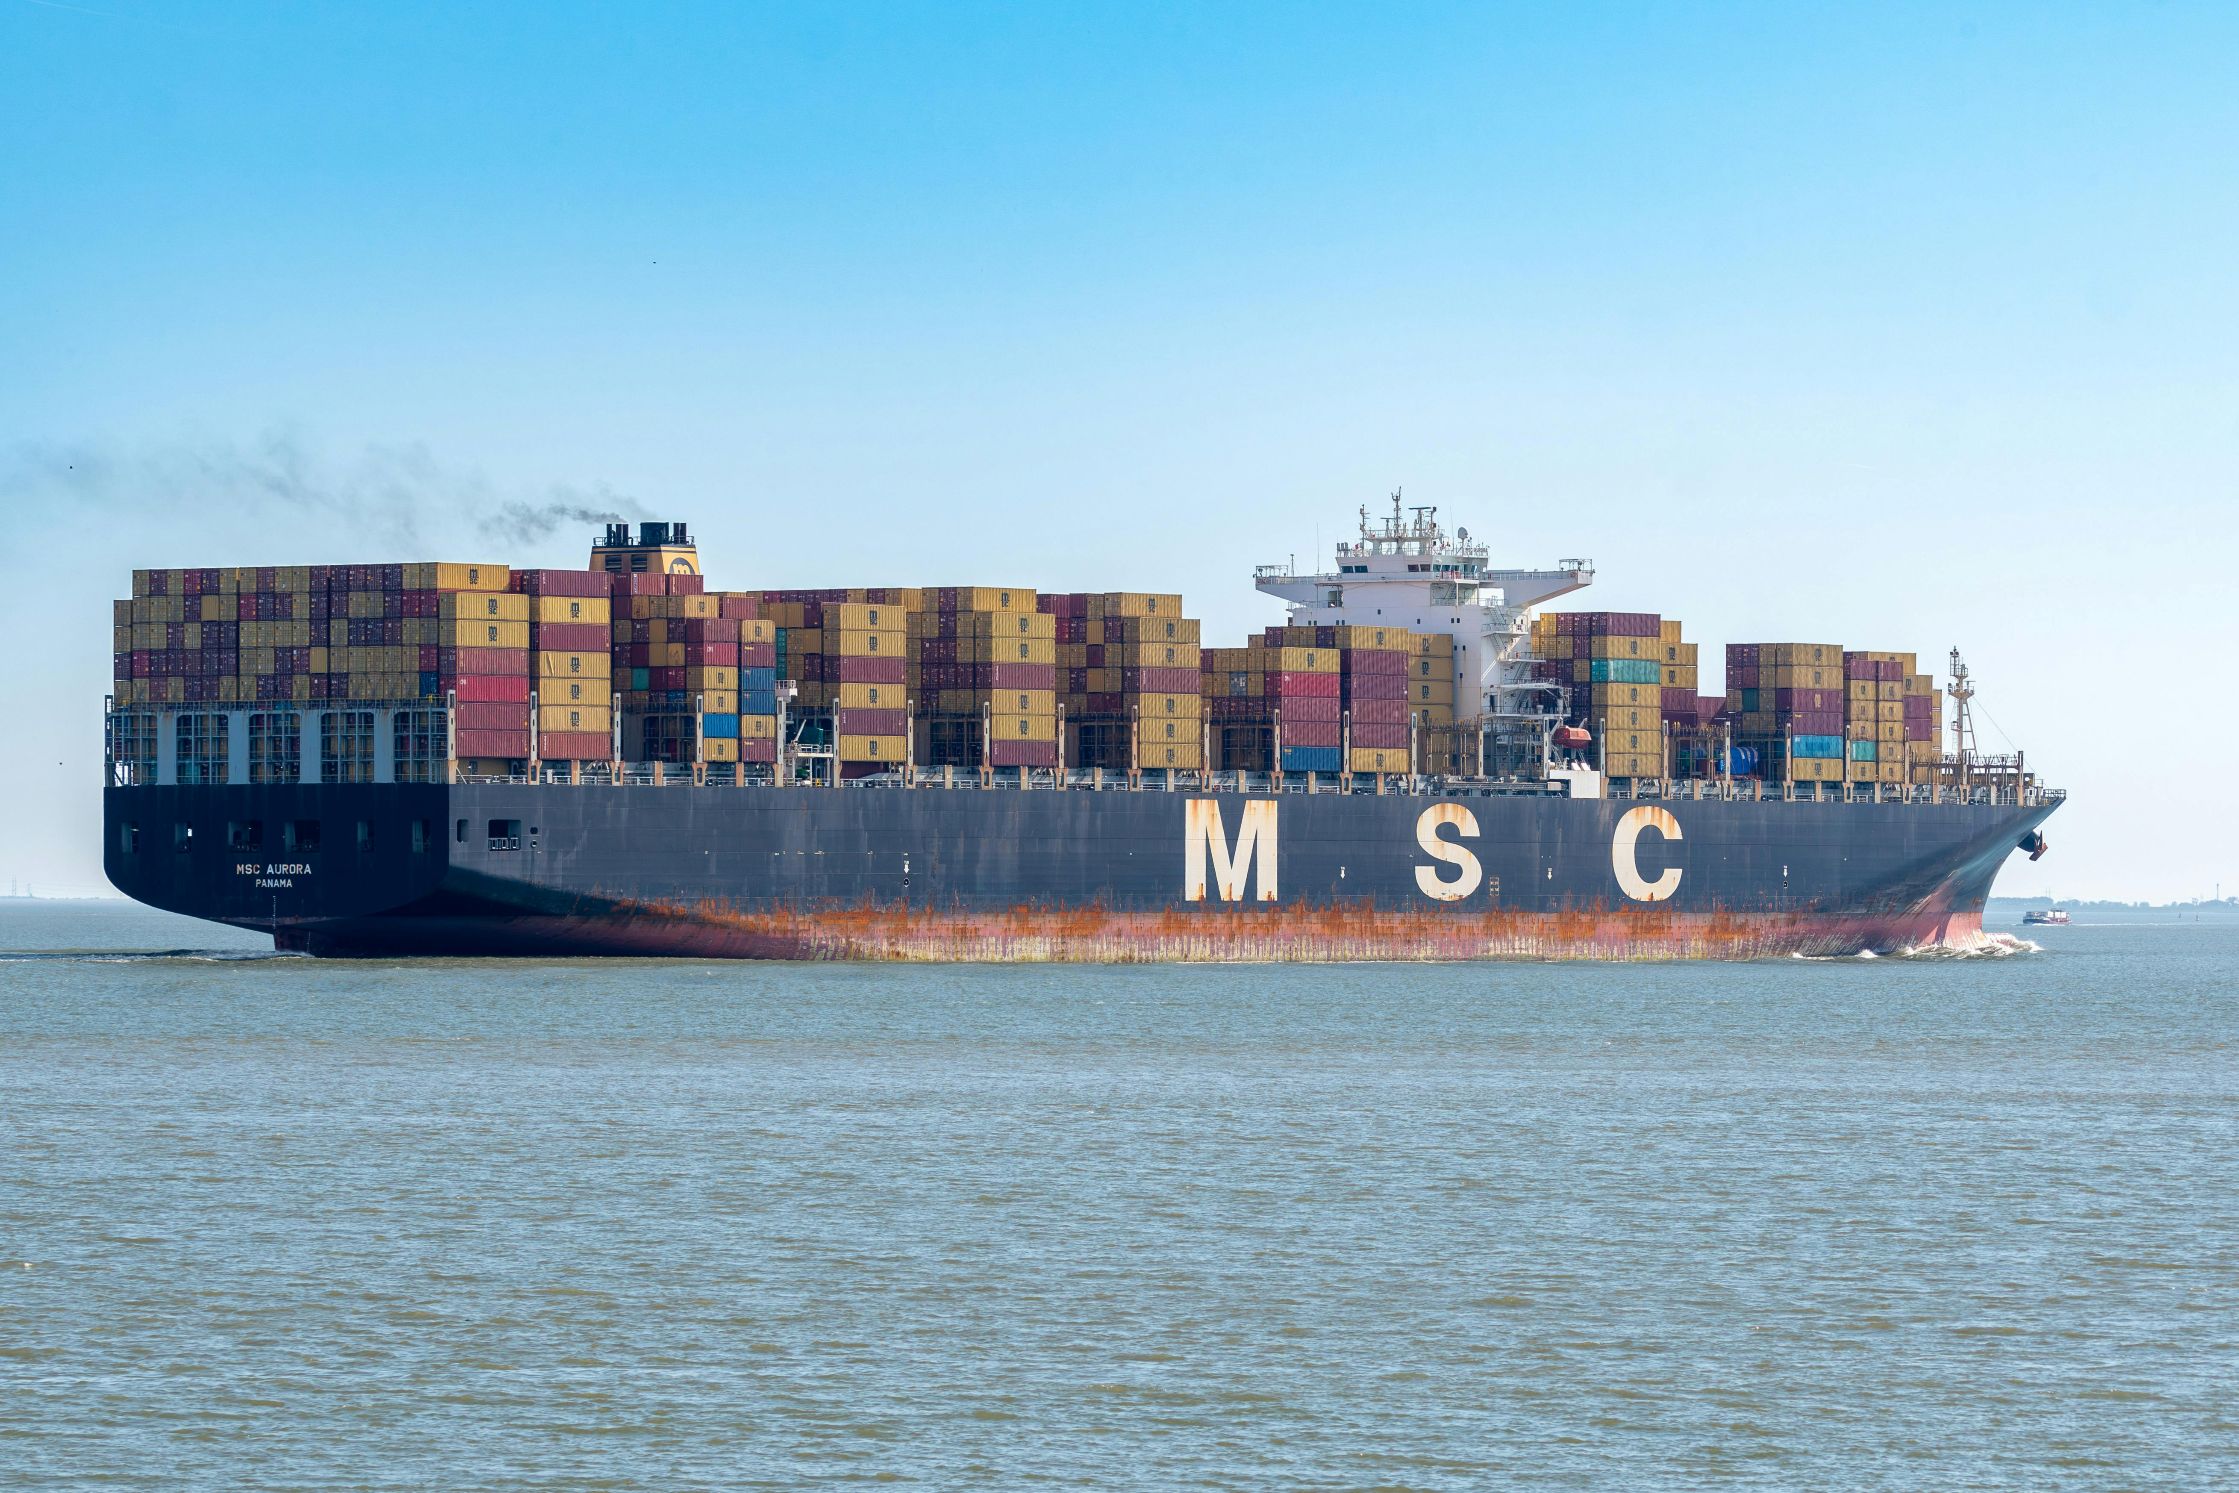
MSC adjusted online quotations upward in mid-October, though actual market acceptance remained below published levels, indicating substantial gap between published rates and actual market acceptance.
Rate negotiation focus is shifting to late October GRI landing verification and the subsequent November-December rate increase cycle. Late October rate support depends critically on holiday-period rolling buildup and post-holiday end-October shipping intensity, as cargo rushes to arrive before Christmas holidays – a timing dynamic distinct from July Christmas cargo patterns.
Capacity Outlook and Space Situation
October weekly average capacity revised downward to 271,000 TEU following increased post-National Day blank sailings, with Weeks 43-44 averaging 301,000 TEU. The downward revision from original projections reflects carriers’ responsive capacity management as post-holiday cargo uptake showed some booking pressure.
November preliminary capacity averages 300,000 TEU weekly with no TBN capacity, though Week 45 capacity drops substantially to 284,000 TEU with multiple blank sailings scheduled:
Premier Alliance FE4/Silk service blank sailing
Ocean Alliance AEU3/FAL2 service blank sailing
Ocean Alliance AEU1/FAL5 service blank sailing
The concentrated Week 45 blank sailing pattern suggests carriers have motivation to increase proactive capacity discipline in early November to support GRI landing, particularly as late October cargo momentum remains uncertain. We anticipate further blank sailing announcements may emerge depending on booking progress through the final week of October.
Cargo loading showed differentiation across carriers during the post-holiday period. COSCO maintained full loading with Shanghai port cargo relatively abundant, mainly automotive cargo. Evergreen Marine similarly operated at full capacity with limited rollovers, demonstrating strong cargo base retention.
MSC Week 42 full loading was primarily supported by Week 41 blank sailing cargo rollover rather than organic demand growth, with Week 43 cargo uptake slowing after rate increases. Premier Alliance Week 42 loading remained tight overall with selective carrier gaps, prompting Yang Ming’s rate reduction to attract cargo.
Maersk booking progress remained moderate with rollovers attributed to passive rolling from schedule delays rather than demand-driven overbooking. Holiday-period rolling buildup across carriers proved mediocre, weakening the foundation for post-holiday rate increase acceptance and creating uncertainty around late October GRI implementation prospects.
Suez Canal Resumption Progress and Regional Security
Red Sea security situation remains contained to Yemen and Saudi Arabia with no signs of expansion, while Suez Canal return process continues accelerating. Approximately 27 percent of Asia-Europe capacity has returned to Red Sea routing, with Suez Canal weekly transits ranging 278-295 vessels, though transit cargo volume at approximately 1.1 million tons daily remains only one-third of 2023 levels.
Premier Alliance FE1, IOX and INX services have returned via Suez, while Maersk and Hapag-Lloyd added AE5, AE11, AE12 and ME2 services via Suez routing during October. Among Asia-Mediterranean services, 11 of 18 tracked services have fully returned via Suez with GEMINI alliance completing full return across all four services (SE2/AE11, SE1/AE12, SE3/AE15, SE4/AE19).
Asia-Northwest Europe resumption remains more limited, with only 2 of 20 tracked services fully returned via Suez. Ocean Alliance operates 5 services on eastbound-only return (FAL2/AEU3, FAL3/AEU6, FAL5/AEU1, FAL7/AEU7, FAL8/AEU9 partially), while GEMINI’s AE5/NE4 has fully returned though AE1/NE2 and AE3/NE3 continue via Cape of Good Hope.
The phased resumption pattern indicates carriers are managing directional risk assessment and selective voyage decisions rather than immediate full-scale transitions. From a medium-term planning perspective, continued resumption progress offers shorter transit times compared to Cape diversions, though security conditions warrant ongoing monitoring.
RS Logistics will continue monitoring carrier pricing strategies, capacity deployment adjustments and Suez Canal resumption developments closely. Our EMEA, Intra-Asia and Oceania Trade teams across China and Southeast Asia remain available to support booking planning, routing evaluation and space coordination for upcoming shipments. We will continue sharing timely updates as market conditions evolve throughout the second half of October.

.svg)